Buying a house is one of the biggest financial decisions in life. For most people in India, taking a home loan is not just an option—it is a necessity. But before you sign any loan agreement, you must clearly understand home loan EMI calculation with a real example.
Many borrowers make the mistake of focusing only on the interest rate. However, your EMI depends on three major factors: loan amount, interest rate, and tenure. A small change in any of these can add or save lakhs of rupees.
In this guide, we will break down everything in simple, everyday language. You will learn how EMI works, see a real-life calculation, understand the tax benefits you’re entitled to, and explore smart strategies to reduce your loan burden — all explained the way a friend who works in banking would explain it to you, not the way your loan officer rushes through it in five minutes.
If you’re also building long-term wealth alongside managing a loan, it’s worth reading our guide on SIP investing and how it builds wealth over time — many borrowers successfully run a modest SIP alongside their EMI rather than treating the two as competing priorities.
What Is Home Loan EMI?
EMI stands for Equated Monthly Installment.
It is the fixed amount you pay every month to repay your home loan. Your EMI automatically includes two components:
- Principal amount – the actual loan you borrowed.
- Interest amount – the cost charged by the bank for lending you money.
Important Pattern to Remember
- In the first few years, the interest portion of your EMI is very high, and the principal repayment is low.
- In the later years, the principal portion becomes higher, and interest reduces.
This structure is called amortization. Banks design it this way to recover their interest early in the loan tenure. It’s a completely standard, regulated practice — not something to be suspicious of — but understanding it changes how you think about prepayment timing, which we’ll get to shortly.
Home Loan EMI Calculation Formula (Standard)
Banks and housing finance companies use a standard mathematical formula to calculate EMI:
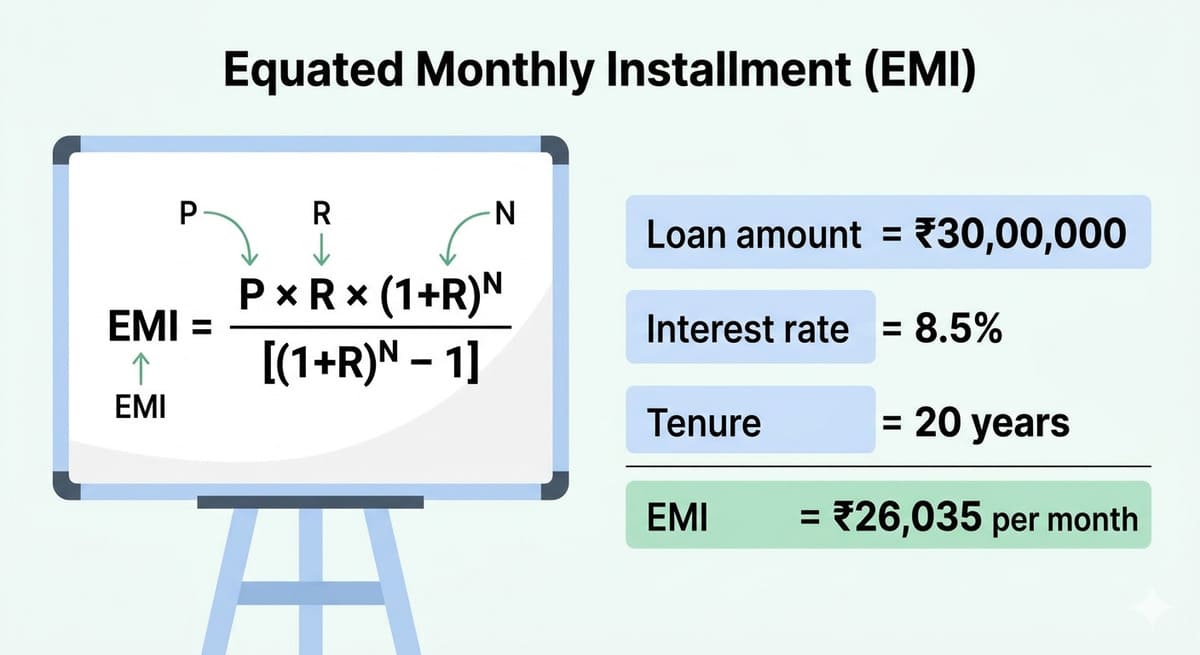
EMI = P × R × (1 + R)^N / [(1 + R)^N – 1]
Where:
- P = Principal loan amount (in rupees)
- R = Monthly interest rate (annual rate ÷ 12 ÷ 100)
- N = Loan tenure in months
Do not worry if the formula looks complicated. Almost nobody calculates this by hand in practice — but understanding what feeds into it is what actually helps you negotiate better terms. Let us now understand it with a real example that you can relate to.
[Image: Home loan EMI calculation example showing formula and monthly payment of ₹26,035 for ₹30 lakh loan at 8.5% for 20 years]
Home Loan EMI Calculation with Real Example
Let us take a typical scenario for a middle-class family in India.
Loan details:
- Loan Amount (P) = ₹30,00,000 (30 lakhs)
- Annual Interest Rate = 8.5% per year
- Loan Tenure = 20 years
Step 1 – Convert annual interest to monthly rate
8.5% ÷ 12 ÷ 100 = 0.007083
Step 2 – Convert tenure into months
20 years × 12 = 240 months
Step 3 – Apply the EMI formula
EMI = 30,00,000 × 0.007083 × (1 + 0.007083)^240 / [(1 + 0.007083)^240 – 1]
After calculation, the EMI comes to approximately:
₹26,035 per month
So, if you take a ₹30 lakh home loan for 20 years at 8.5% interest, you will pay around ₹26,000 every month for the next 20 years — every single month, without exception, until the loan closes or you prepay it.
Total Interest You Will Pay – The Reality Check
Many borrowers forget to calculate total interest. Let us do that now.
- Monthly EMI = ₹26,035
- Total months = 240
- Total repayment = ₹26,035 × 240 = ₹62,48,400
- Loan amount (principal) = ₹30,00,000
- Total interest paid = ₹32,48,400
Yes, you read that correctly. You are paying more than the principal amount in interest alone.
This is exactly why understanding home loan EMI calculation with a real example is so important before signing any loan agreement. On paper, a ₹30 lakh loan sounds like a ₹30 lakh commitment. In reality, at these terms, it’s closer to a ₹62 lakh commitment once interest is added.
EMI Breakdown: First Year vs Last Year
Let us see how your EMI is divided over time.
In the first year:
- Interest portion: very high (~80% of EMI)
- Principal portion: very low (~20% of EMI)
After 10 years:
- Interest and principal become roughly equal
In the last year:
- Principal portion: very high (~95% of EMI)
- Interest portion: very low (~5% of EMI)
This means if you try to close your loan early, you save a lot of interest. But if you close it very late, most of the interest has already been paid, and prepaying at that stage saves comparatively little.
A Simplified Amortization Snapshot
To make this pattern concrete, here’s roughly how the same ₹30 lakh loan at 8.5% for 20 years splits between interest and principal at different stages:
| Loan Year | Approx. Interest Portion | Approx. Principal Portion |
|---|---|---|
| Year 1 | ~₹25,300/month | ~₹700/month |
| Year 5 | ~₹22,800/month | ~₹3,200/month |
| Year 10 | ~₹18,500/month | ~₹7,500/month |
| Year 15 | ~₹11,200/month | ~₹14,800/month |
| Year 20 | ~₹1,800/month | ~₹24,200/month |
(Figures are illustrative approximations based on standard amortization patterns — always request your bank’s exact amortization schedule for precise numbers.)
This table is the single most useful thing to internalize from this entire article: your EMI amount stays fixed, but what it’s actually paying for shifts dramatically over the life of the loan.
How Interest Rate Affects Your EMI
A small difference in interest rate has a big impact. Let us compare the same ₹30 lakh loan for 20 years at different rates.
| Interest Rate | Monthly EMI | Total Interest |
|---|---|---|
| 8.0% | ₹25,093 | ₹30,22,320 |
| 8.5% | ₹26,035 | ₹32,48,400 |
| 9.0% | ₹26,995 | ₹34,78,800 |
Key takeaway: Even a 0.5% increase adds over ₹2 lakh to your total interest. This is precisely why it’s worth spending a few extra days shopping around for a better rate before signing, rather than accepting the first offer out of convenience.
How Loan Tenure Affects Your EMI
You can choose a shorter or longer tenure. Each has trade-offs.
Example: ₹30 lakh loan at 8.5% interest
| Tenure | Monthly EMI | Total Interest |
|---|---|---|
| 15 years | ₹29,537 | ₹23,16,660 |
| 20 years | ₹26,035 | ₹32,48,400 |
| 25 years | ₹24,142 | ₹42,42,600 |
| 30 years | ₹23,067 | ₹53,04,120 |
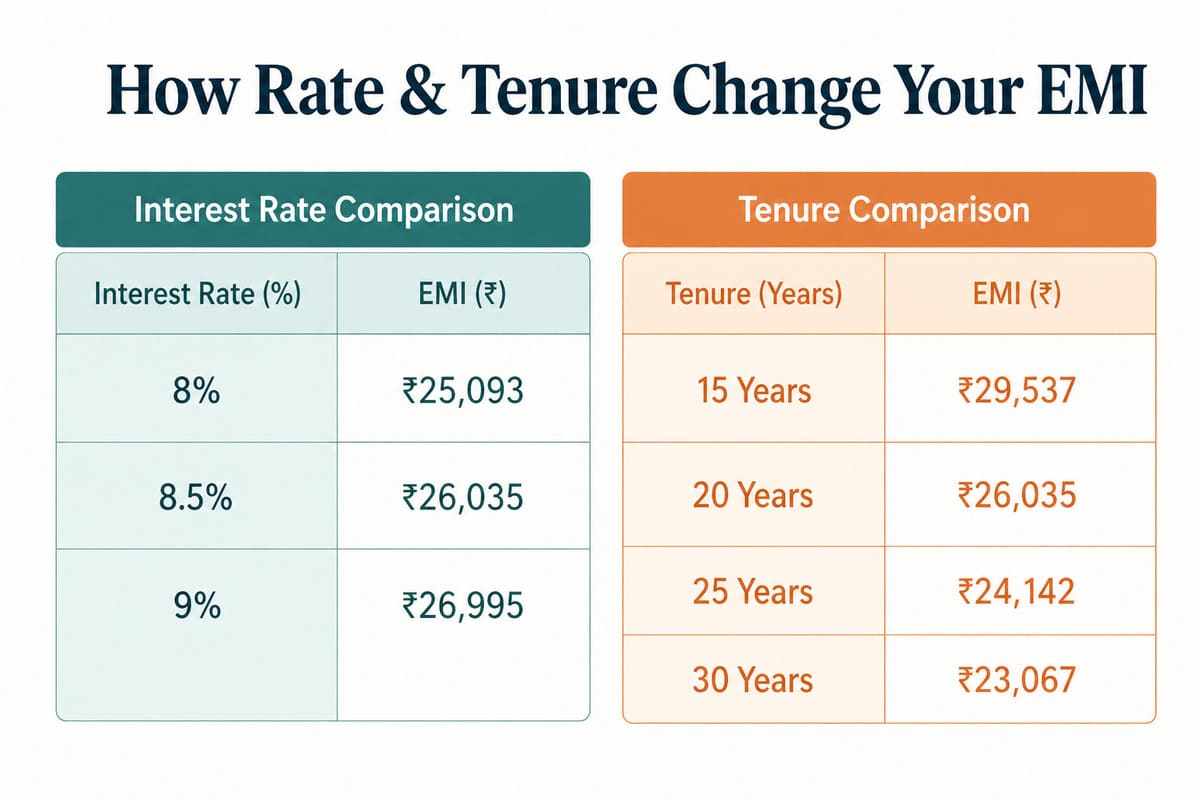
- Shorter tenure = higher EMI but much lower total interest.
- Longer tenure = lower EMI but much higher total interest.
Smart rule: Choose the shortest tenure you can comfortably afford, not the longest tenure that makes the EMI look small on paper.
Before applying, always check your CIBIL score, as it directly impacts your interest rate.
Types of Home Loans You Should Know About
Not every home loan is structured the same way. Understanding the main categories helps you ask your bank the right questions:
- Regular Home Loan – for purchasing a ready or under-construction residential property.
- Home Construction Loan – disbursed in stages as construction progresses, rather than as a single lump sum.
- Home Improvement/Renovation Loan – for repairs, extensions, or upgrades to an existing property.
- Home Extension Loan – specifically for adding new rooms or floors.
- Balance Transfer Loan – for moving your existing loan to another lender offering a better rate (covered in detail below).
- Top-Up Loan – additional funds sanctioned on top of your existing home loan, usually at home-loan interest rates rather than the higher rates of personal loans.
- PMAY-Linked Loans – for eligible first-time buyers, offering interest subsidies under the Pradhan Mantri Awas Yojana scheme, subject to income and eligibility criteria.
Documents Typically Required for a Home Loan
While requirements vary slightly by lender, most banks and housing finance companies ask for:
- Identity proof – PAN card, Aadhaar card, passport, or voter ID
- Address proof – utility bills, Aadhaar, or rental agreement
- Income proof – salary slips (last 3–6 months) for salaried applicants, or ITR and profit/loss statements for self-employed applicants
- Bank statements – usually the last 6 months
- Property documents – sale agreement, title deed, approved building plan, and NOC from the builder or society
- CIBIL/credit report – most banks pull this directly, but checking your own score beforehand helps you negotiate
Having these ready before you apply can meaningfully speed up loan approval and reduces back-and-forth delays with the bank.
Tax Benefits on Home Loan EMI (India)
This is one of the most overlooked parts of home loan planning. Under current Indian tax law, home loan borrowers can claim benefits under a few key sections:
- Section 24(b) – Deduction on interest paid, up to a specified annual limit, for a self-occupied property.
- Section 80C – Deduction on principal repayment, within the overall Section 80C limit (which also covers other investments like ELSS and PPF).
- Section 80EEA – Additional deduction for first-time home buyers on affordable housing loans, subject to eligibility conditions.
These deduction limits and eligibility rules are revised periodically in the Union Budget, so it’s worth checking the latest figures directly on the Income Tax Department’s official website or consulting a tax professional before assuming a specific number applies to your situation.
Also worth noting: if you’re using ELSS funds to make the most of your 80C limit alongside your home loan principal repayment, our guide on mutual funds for beginners is a useful next read.
Should You Use an EMI Calculator?
Instead of manual math, always use an online EMI calculator. It is fast, free, and accurate.
You can find reliable calculators on:
- RBI website – for official awareness and regulatory updates
- SEBI investor portal – for unbiased financial calculators and investor education
✅ Always check at least two different EMI calculators before finalizing your loan, since small rounding or compounding-method differences between tools can shift the displayed number slightly.
[Image: Comparison chart showing how interest rate and tenure affect home loan EMI and total interest for a ₹30 lakh loan]
Smart Tips Before Taking a Home Loan
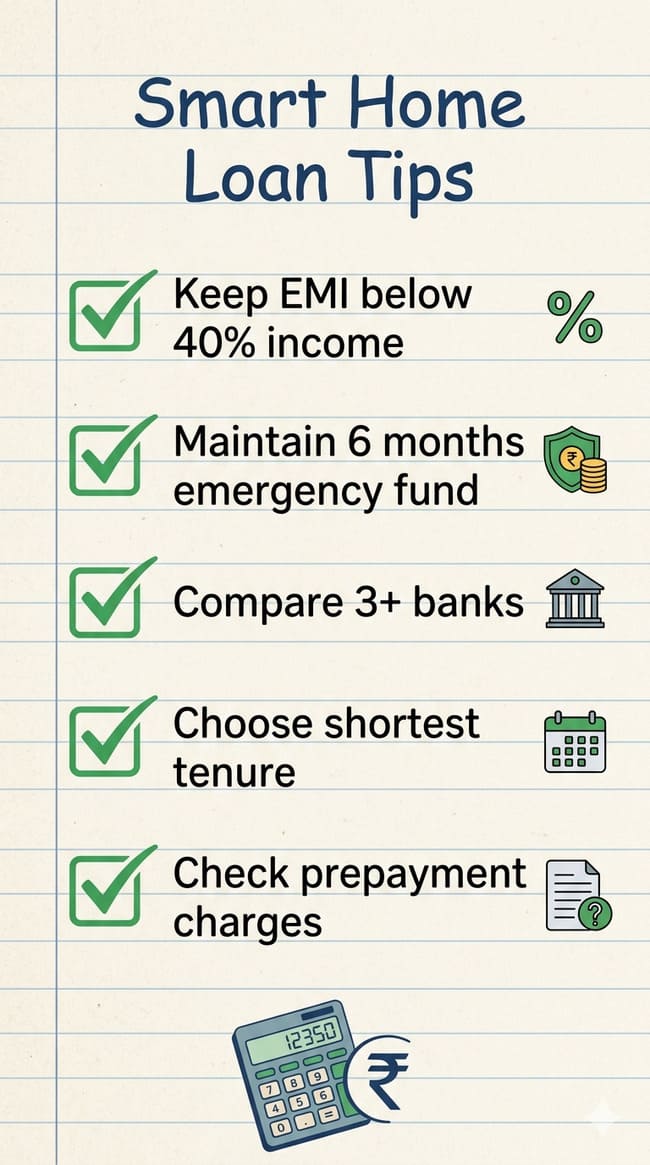
Follow these practical rules to stay financially safe.
1. Keep EMI Below 40% of Your Monthly Income
If your monthly income is ₹70,000, your home loan EMI should not exceed ₹28,000. This isn’t an arbitrary number — it’s roughly the threshold most banks themselves use internally when assessing loan eligibility, and going beyond it leaves little room for other financial goals or emergencies.
2. Maintain an Emergency Fund
Keep at least 6 months of EMI in a separate savings account. A home loan is a multi-decade commitment; a job loss or medical emergency shouldn’t immediately put your house at risk.
3. Compare at Least 3 Banks
Do not accept the first offer. Public banks, private banks, and NBFCs all have different rates, and the difference between the best and worst offer available to you can easily run into several lakhs over the loan’s lifetime.
4. Check Prepayment and Foreclosure Charges
Many banks do not charge for floating-rate loans, as per RBI guidelines. Avoid loans with high prepayment penalties, especially if you anticipate having surplus funds down the line.
5. Read the Loan Amortisation Schedule
This is a table showing exactly how much principal and interest you pay each month. Ask your bank for it — it’s your right as a borrower, and it removes any ambiguity about where your money is actually going each month.
[Image: Smart tips checklist for home loan borrowers including EMI below 40% income, emergency fund, compare banks, and prepayment benefits]
Can You Reduce Your Home Loan EMI After Taking It?
Yes, you can reduce your EMI in several ways:
- Make a partial prepayment – pay extra whenever you have surplus money.
- Increase your down payment at the time of purchase.
- Negotiate a lower interest rate with your existing bank.
- Transfer your loan to another bank offering a lower rate (balance transfer).
- Reduce tenure instead of EMI – this saves more interest.
Even one extra EMI payment every year can reduce your loan tenure by several years.
A Quick Prepayment Example
Say you’re 5 years into the ₹30 lakh, 20-year loan at 8.5% used earlier, and you make a lump-sum prepayment of ₹2 lakh toward the principal. Because you’re prepaying while the interest portion of your EMI is still relatively high, this single payment can shave a meaningful chunk off your total interest and shorten your effective tenure by roughly a year or more, depending on your bank’s recalculation method (either reduced EMI or reduced tenure — most banks let you choose). This is precisely why the “amortization pattern” discussed earlier matters: prepaying early in the loan is disproportionately more valuable than prepaying late.
Fixed vs Floating Interest Rate – Which Is Better?
Fixed Interest Rate:
- EMI remains constant throughout the tenure.
- Safe during rising interest rate markets.
- Usually 1–2% higher than floating rates.
Floating Interest Rate:
- EMI changes when RBI changes the repo rate.
- Can go up or down.
- Historically cheaper over long periods.
Recommendation: Most salaried borrowers should choose a floating rate for a 15–20 year loan because it offers flexibility and lower initial cost. That said, if you strongly value payment predictability over potential savings, a fixed rate isn’t a wrong choice — it’s a different trade-off, not an inferior one.
Interest rates change based on the repo rate set by the Reserve Bank of India.
Home Loan Balance Transfer: When Does It Actually Make Sense?
A balance transfer means moving your existing loan to a new lender who offers a lower interest rate. It sounds like an easy win, but it’s only worth it under certain conditions:
- Early in the loan tenure – since that’s when the interest portion of your EMI is highest, a rate cut has the most impact.
- The rate difference is meaningful – generally, a difference of 0.5% or more makes the switch worth considering, after accounting for processing fees.
- Processing and legal charges don’t wipe out the savings – new lenders often charge processing fees (typically 0.5%–1% of the loan amount) plus legal and valuation charges. Calculate the net savings after these costs, not just the headline rate difference.
- You have several years of tenure remaining – a balance transfer late in a loan’s life rarely makes financial sense, since most of the interest has already been paid.
If all of these line up, a balance transfer can genuinely save you lakhs. If they don’t, it’s often more effort than it’s worth.
Common Mistakes to Avoid
- ❌ Taking a longer tenure just to get a lower EMI.
- ❌ Ignoring total interest payable.
- ❌ Not checking processing fees and hidden charges.
- ❌ Applying for a loan without checking your CIBIL score first.
- ❌ Believing that a lower EMI means a better loan.
- ❌ Skipping the fine print on prepayment penalties.
- ❌ Not accounting for the EMI in your broader monthly budget alongside other financial goals, like an ongoing SIP or emergency fund contribution.
Final Thought
Understanding home loan EMI calculation with a real example is not just a mathematical exercise—it is a financial survival skill. A home loan is a 15-to-30-year commitment. A small mistake in tenure or rate can cost you lakhs of rupees.
Before applying for any housing loan, always calculate:
- Monthly EMI
- Total interest payable
- Impact on your monthly budget
Then ask yourself honestly: Can I pay this EMI for 20 years without stress?
If yes, you are ready. If not, wait, save more, or choose a smaller loan.
Borrow wisely. Plan carefully. And always keep learning.
Frequently Asked Questions (FAQ)
1. What is EMI in a home loan?
Ans- EMI is the fixed monthly amount you pay to repay both principal and interest.
2. How is home loan EMI calculated?
Ans- It is calculated using principal, interest rate, and tenure with the formula:
EMI = P × R × (1 + R)^N / [(1 + R)^N – 1]
3. Does a longer tenure reduce EMI?
Ans- Yes, but it increases total interest paid significantly.
4. Can I reduce my home loan EMI after taking the loan?
Ans – Yes, by prepaying, negotiating a lower rate, or transferring the loan to another lender.
5. Is EMI affected by floating interest rates?
Ans – Yes, RBI policy changes can increase or decrease your EMI under a floating-rate loan.
6. What is a good EMI-to-income ratio?
Ans – Ideally, home loan EMI should not exceed 40% of your monthly take-home salary.
7. What tax benefits can I claim on my home loan?
Ans – You may be eligible for deductions under Section 24(b) on interest paid and Section 80C on principal repaid, with an additional benefit under Section 80EEA for eligible first-time buyers — subject to current limits and conditions.
8. Is it better to prepay the loan or invest the surplus instead?
Ans – This depends on your loan’s interest rate versus your expected investment returns, your risk tolerance, and your emotional comfort with debt. As a rough guide, if your loan interest rate is higher than what you’d reliably earn elsewhere after tax, prepayment often makes more mathematical sense — but many people also value the peace of mind of being debt-free sooner.
9. What documents are needed for a home loan balance transfer?
Ans – Generally the same documents as a fresh loan application, plus your existing loan statement, foreclosure letter, and property documents from your current lender.
10. Does my CIBIL score affect my EMI amount?
Ans – Indirectly, yes. A higher CIBIL score typically qualifies you for a lower interest rate, which directly reduces your EMI and total interest payable. If your score needs work, here’s how to improve your CIBIL score from 550 to 750.
Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice. Interest rates, tax laws, and bank policies change over time. Please consult your bank or a SEBI-registered financial advisor before making any home loan decision.
Shilpesh Rathod
Shilpesh Rathod is the founder of All Finance Knowledge. He holds a B.Com degree along with JAIIB and CAIIB banking certifications, and brings 19+ years of experience in the banking sector across savings, investments, and financial planning.

Shilpesh Rathod is the founder of All Finance Knowledge. He holds a B.Com degree along with JAIIB and CAIIB banking certifications, and brings 19+ years of experience in the banking sector across savings, investments, and financial planning. Read more: https://allfinanceknowledge.com/about-us/
7 thoughts on “Home Loan EMI Calculation with Real Example: A Complete Guide for 2026”