Most of us have had that moment on the 25th of the month — salary already gone, credit card bill staring back, and a vague sense that we earn “enough” but somehow never save enough. If that sounds familiar, you’re not bad with money. You just don’t have a system.
The 50-30-20 rule in India is one of the simplest systems around, and it works whether you take home ₹20,000 a month or ₹2,00,000. This guide walks through exactly how to apply it to an Indian salary, with real numbers, city comparisons, low-income adjustments, and the mistakes that trip up most beginners. If you’re completely new to this space, it’s worth starting with our guide on what personal finance actually means before diving into the numbers below.
What Is the 50-30-20 Rule?
The 50-30-20 rule splits your take-home (in-hand) salary — not your CTC — into three buckets:
| Bucket | % of income | What it covers |
|---|---|---|
| Needs | 50% | Rent, groceries, EMIs, utilities, insurance |
| Wants | 30% | Eating out, OTT, shopping, travel |
| Savings & Investments | 20% | SIPs, PPF, EPF, NPS, emergency fund |
The rule was popularised by U.S. Senator Elizabeth Warren in her book All Your Worth, but the underlying logic — spend on essentials, allow yourself some lifestyle spending, and pay your future self first — translates well to Indian households, provided you adjust it for local realities like high metro rents and joint family expenses.
Why This Rule Works Especially Well in India
Indian salaried life comes with a specific set of pressures:
- Rising cost of living, especially rent and school fees in metros
- EMIs — home loans, car loans, personal loans, consumer durable EMIs
- Family responsibilities — supporting parents, siblings, or in-laws
- Irregular income spikes — annual bonuses, Diwali gifts, incentives that tempt overspending
The 50-30-20 rule works well here because it doesn’t ask you to track every single rupee (which most people give up on within two weeks). Instead, it gives you three wide lanes to stay within — a system people can actually sustain.
50-30-20 Rule Explained with an Indian Salary Example
Let’s start with the classic example.
Monthly take-home salary: ₹50,000
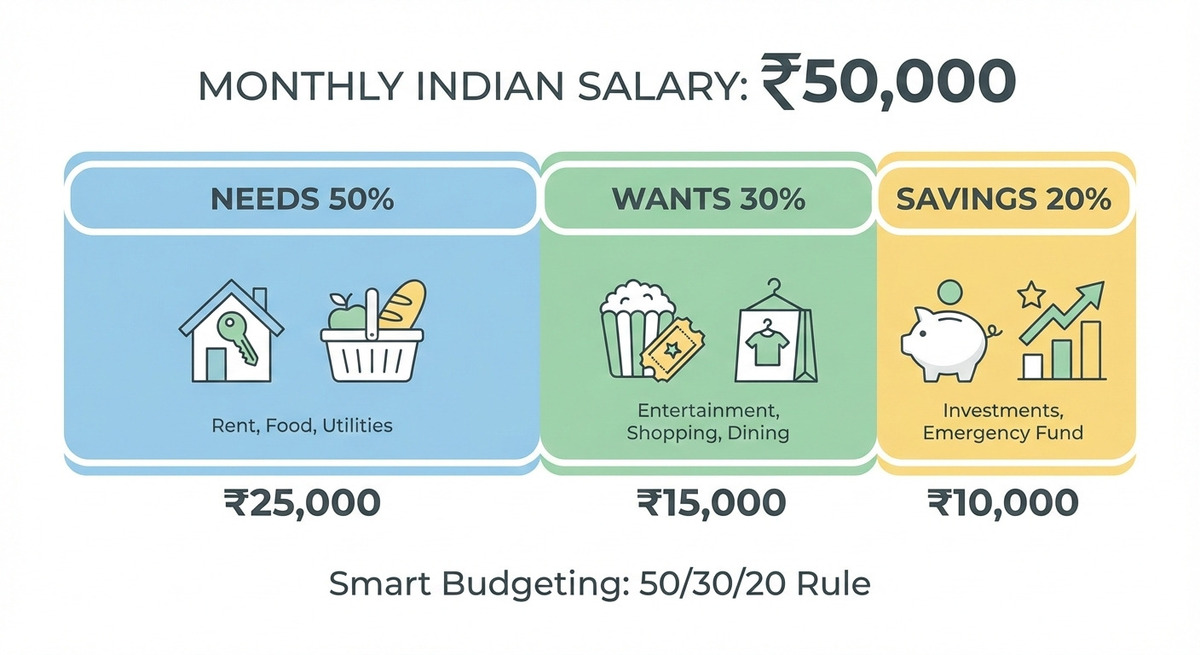
- 50% Needs = ₹25,000
- 30% Wants = ₹15,000
- 20% Savings = ₹10,000
Now let’s break each slice down into real line items, the way an actual Indian household would spend it.
50% – Needs (₹25,000)
Needs are the expenses you genuinely can’t skip without consequences.
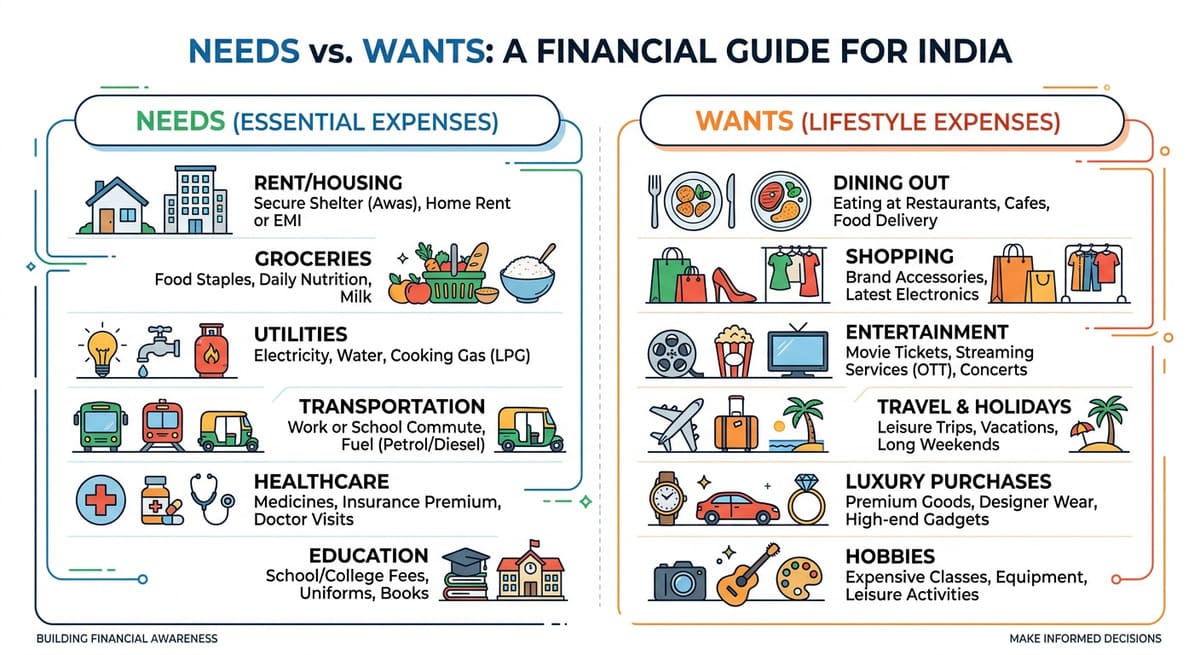
Typical needs in an Indian household:
- House rent or home loan EMI
- Groceries and daily food expenses
- Electricity, water, and cooking gas
- Mobile and internet bills
- School or college fees
- Basic commute (bus, metro, fuel)
- Health and term insurance premiums
Sample Allocation (₹25,000)
| Item | Amount |
|---|---|
| Rent | ₹12,000 |
| Groceries | ₹6,000 |
| Utilities & mobile | ₹2,500 |
| Transport | ₹2,000 |
| Insurance | ₹2,500 |
| Total | ₹25,000 |
If your needs are eating up more than 50–55% of your income (very common in metros), the fix usually isn’t “spend less on groceries” — it’s structural: a smaller home, a shared flat, renegotiating an EMI tenure, or a cheaper locality with a longer commute.
30% – Wants (₹15,000)
Wants are what make life enjoyable, not just survivable. This bucket is not something to feel guilty about — it exists by design.
Typical wants:
- Eating out and food delivery
- OTT subscriptions (Netflix, Prime, Hotstar)
- Shopping for clothes and gadgets
- Weekend trips and vacations
- Gym or fitness memberships
- Hobbies and entertainment
Sample Allocation (₹15,000)
| Item | Amount |
|---|---|
| Dining out | ₹4,000 |
| OTT & apps | ₹1,000 |
| Shopping | ₹5,000 |
| Movies & outings | ₹3,000 |
| Miscellaneous | ₹2,000 |
| Total | ₹15,000 |
A common mistake is quietly letting “wants” bleed into the needs column — calling a food delivery habit a “grocery expense.” Being honest about this split is what makes the rule actually useful.
20% – Savings & Investments (₹10,000)
This is the bucket that builds your future, and it’s the one most people shrink first when money feels tight — which is exactly backwards. It’s also worth understanding early on that saving money alone isn’t enough — this 20% needs to eventually move from a plain savings account into instruments that actually beat inflation.
Where Indians typically direct this 20%:
- Emergency fund (until it covers 3–6 months of expenses)
- SIPs in mutual funds
- Public Provident Fund (PPF)
- Employee Provident Fund (EPF)
- National Pension System (NPS)
- Fixed Deposits (FDs) and Recurring Deposits (RDs)
Sample Allocation (₹10,000)
| Item | Amount |
|---|---|
| SIP in equity mutual fund | ₹5,000 |
| PPF / EPF | ₹3,000 |
| Emergency fund | ₹2,000 |
| Total | ₹10,000 |
If you’re deciding where that SIP amount should actually go, our comparison of index funds vs large-cap funds is a good next read — both are common choices for this slice of the 20%.
The golden rule here: pay yourself first. Set up an auto-debit or SIP mandate for the day after your salary is credited, so the money leaves before it has a chance to get spent.
50-30-20 Rule vs Traditional Budgeting
Most Indian households don’t budget with percentages at all — they just spend as needs arise and save whatever’s left, if anything.
Problems with Traditional Budgeting
- No fixed savings target
- Lifestyle spending creeps up unnoticed
- Savings only happen when money happens to be left over
- Tracking every single expense is exhausting and rarely sustained
Advantages of the 50-30-20 Rule
- A clear, upfront allocation of income
- Savings become a habit, not an afterthought
- Better financial discipline with far less mental effort
- Less day-to-day anxiety about money
You’re not tracking every rupee — you’re managing three buckets. That’s a much lower-friction habit to build.
Step-by-Step: Building Your Monthly Budget
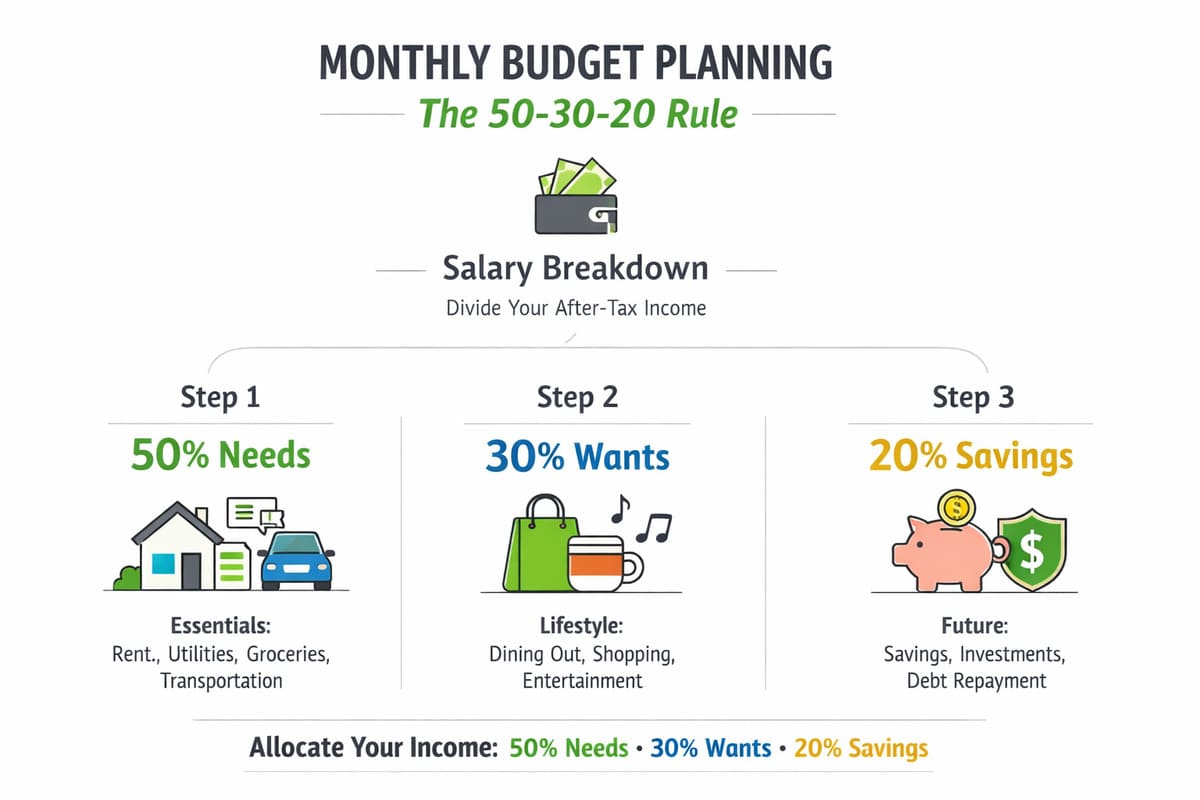
- Calculate your take-home salary. Always use in-hand pay, after tax and PF deductions — not CTC.
- Split it into three categories using 50-30-20 (or an adjusted ratio — more on that below).
- Track your expenses, even loosely, using an app or a simple notebook.
- Adjust where needed. If needs are running over 50%, trim wants first before touching savings.
- Automate your savings. Move the 20% out on salary day, before you can spend it.
Real-Life Example: Metro City vs Small Town
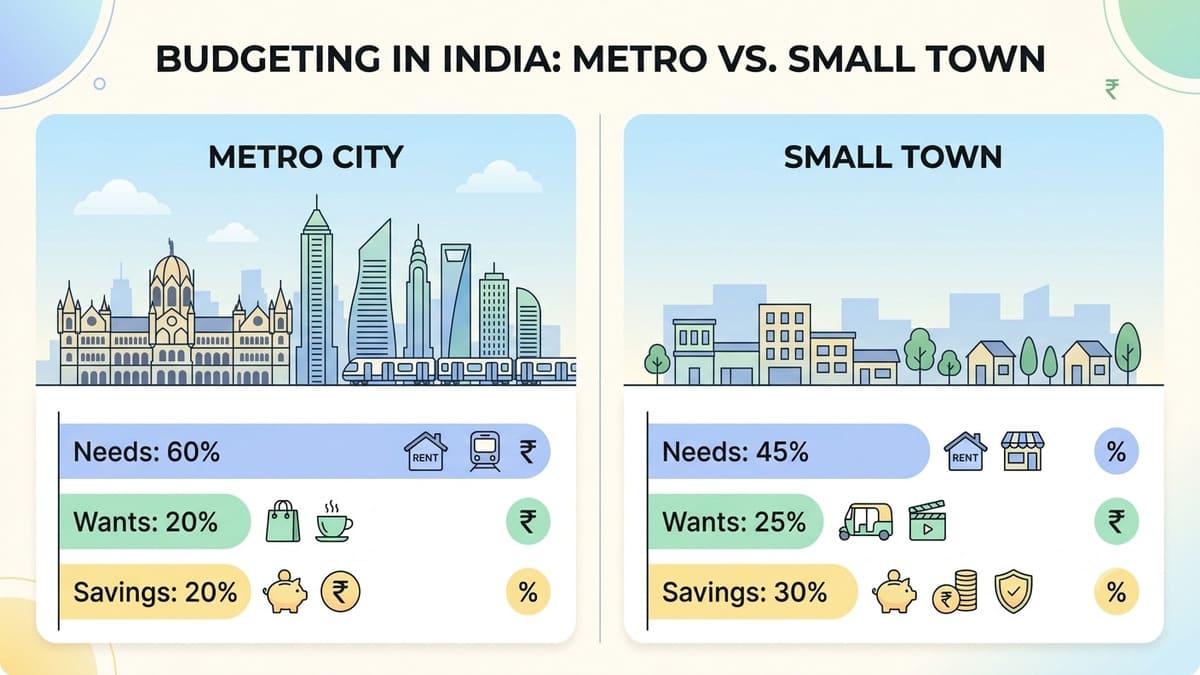
Where you live changes the math significantly.
Metro City (Mumbai, Bengaluru, Delhi NCR)
Salary: ₹60,000
- Needs: ₹35,000–₹40,000 (rent dominates)
- Wants: ₹10,000–₹15,000
- Savings: ₹5,000–₹10,000
Small Town or Tier-2 City
Salary: ₹40,000
- Needs: ₹18,000–₹22,000
- Wants: ₹8,000–₹10,000
- Savings: ₹8,000–₹12,000
Notice that the small-town earner, despite a lower salary, often saves a higher percentage simply because rent takes a smaller bite. Cost of living matters more than the headline salary number — adjust your percentages based on your actual city, not the textbook ratio.
How to Apply the 50-30-20 Rule on a Low Salary
If you’re earning ₹20,000–₹30,000 a month, a strict 50-30-20 split can feel unrealistic, especially in an expensive city. A more workable version is:
- 60% Needs
- 20% Wants
- 20% Savings
Even at this level, protect the savings percentage as much as you can. Saving just ₹1,000–₹2,000 a month, invested consistently, compounds meaningfully over 10–15 years. For a full walkthrough of this exact income range, see our detailed guide on how to plan a monthly budget on a ₹30,000 salary.
How to Increase Savings Beyond 20%
Once the basic habit is in place, here’s how to push past 20%:
- Grow your income — freelancing, upskilling, a side hustle
- Resist lifestyle inflation — when your salary jumps, let savings jump with it, not just spending
- Audit subscriptions — cancel the OTT platforms and apps you forgot you were paying for
- Direct bonuses toward investing instead of one-time splurges
- Prioritise paying down high-interest debt — credit card debt in particular, since its interest cost usually outpaces any investment return
Even moving from 20% to 30% savings can meaningfully compress the number of years it takes to hit a big goal like a house down payment or early retirement.
The Role of an Emergency Fund
Before you get aggressive with SIPs and equity investments, build a cash cushion. This is non-negotiable groundwork.
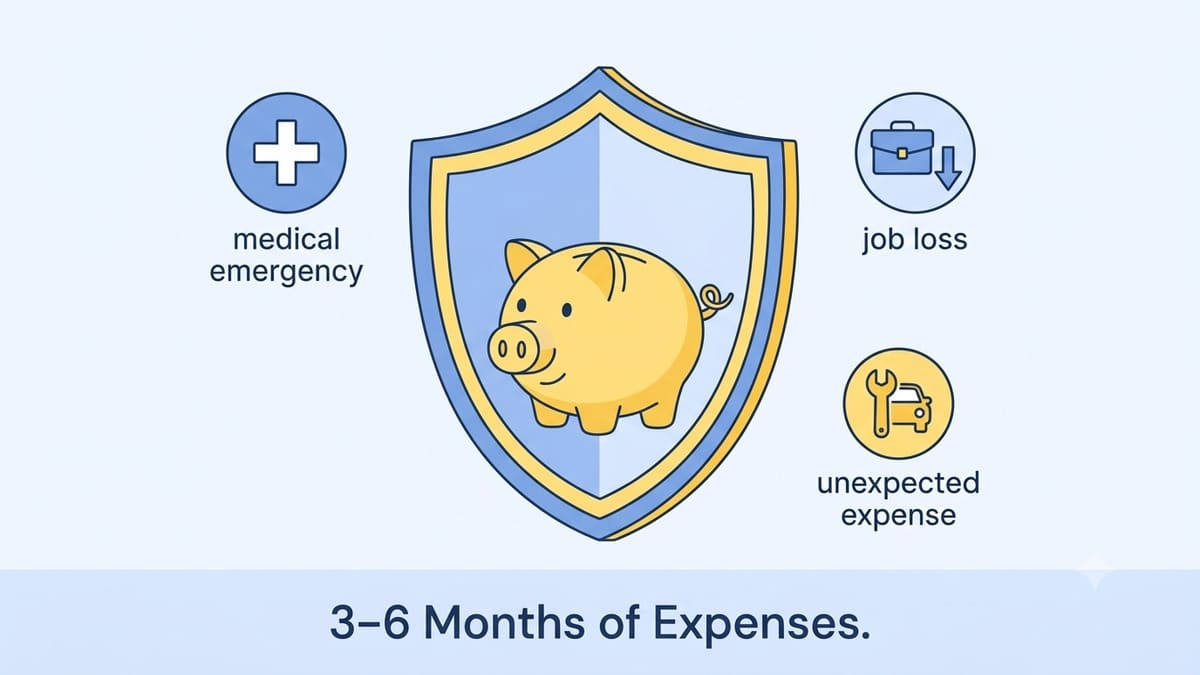
What It Protects You From
- Medical emergencies
- Sudden job loss
- Unplanned big expenses (car repair, family emergency)
Ideal Fund Size
3–6 months of essential expenses.
Where to Keep It
- A separate savings account (so it’s not mixed with spending money)
- A short-term fixed deposit
- A liquid mutual fund, for slightly better returns with easy access
Skipping this step is the single biggest reason people are forced to break long-term investments or take on high-interest debt the moment life throws a curveball.
How the 50-30-20 Rule Supports Your Financial Goals
The 20% savings bucket isn’t just a number — it’s the engine behind every financial goal you have.
Short-Term Goals (0–2 years)
- A new phone
- Travel
- Building the emergency fund
Medium-Term Goals (2–5 years)
- Car purchase
- Higher education
- Wedding expenses
Long-Term Goals (5+ years)
- House down payment
- Retirement
- Children’s education
Mapping specific goals to specific slices of that 20% — say, ₹3,000 into a retirement SIP and ₹2,000 into a “house fund” — makes the abstract habit of “saving 20%” feel concrete and motivating.
Common Mistakes Indians Make While Budgeting
- Not clearly separating needs from wants (calling Swiggy orders “food expenses”)
- Ignoring inflation when reviewing the budget year over year
- Never revisiting the budget once it’s set
- Overspending during festival sales and end-of-season discounts
- Keeping savings flat even as income rises
- Treating EMIs as optional when they’re actually fixed, unavoidable needs
Digital Tools to Track Your Budget
You don’t need anything fancy — consistency matters more than sophistication.
- Expense-tracking apps like Walnut or Money Manager
- Your bank’s own app-based spend categorisation
- ET Money or similar personal finance apps for consolidated tracking
- A plain Excel sheet or Google Sheet
- A physical notebook, if that’s what you’ll actually stick to
For anyone investing through mutual funds, it’s also worth getting familiar with SEBI’s investor education resources to understand risk categories before picking a fund.
50-30-20 Rule for Families vs Singles
Singles
- More room in the “wants” bucket
- Fewer fixed responsibilities
- Easier path to saving 20% or more
Families
- Higher needs — children’s school fees, larger EMIs, dependent parents
- Savings may start below 20% and should grow steadily with income
The rule is a framework, not a rulebook. Bend the percentages to your real life, then hold yourself accountable to whatever split you land on.
50-30-20 Rule vs Other Budgeting Methods
| Method | How it works | Best for |
|---|---|---|
| Zero-based budget | Every rupee assigned a specific job | Detail-oriented planners, higher time investment |
| Envelope method | Cash divided into physical/digital “envelopes” per category | Strong spenders who need hard limits |
| 50-30-20 rule | Income split into three broad percentages | Beginners wanting a simple, flexible system |
For most first-time budgeters, 50-30-20 wins on simplicity — you can start today with just your salary slip and a calculator.
Benefits of the 50-30-20 Rule
- Simple enough for a complete beginner to start immediately
- Reduces the mental load and stress of money management
- Builds a disciplined savings habit by default
- Naturally increases financial awareness over time
- Flexible enough to work at nearly any Indian income level
FAQs on the 50-30-20 Rule
1. Is the 50-30-20 rule suitable for Indians?
Ans – Yes — it works well once adapted to local realities like rent levels and family responsibilities, rather than applied rigidly.
2. Can I change the percentages?
Ans – Absolutely. The ratio is a starting point, not a law. Adjust it to your income, city, and life stage.
3. Does the rule include tax?
Ans – No — apply it to your take-home (post-tax, post-PF) salary, not your CTC.
4. Is saving 20% mandatory?
Ans – It’s the recommended target, but even 10–15% is a solid starting point if 20% isn’t realistic yet.
5. Can business owners or freelancers use this rule?
Ans – Yes — apply it to your average monthly income over the last 6–12 months rather than a single month’s figure.
Q6. Can I follow 50-30-20 rule with irregular income?
Ans – Yes. Use a trailing average of your last few months’ income as your base number.
Q7. Should EMIs be counted as “needs”?
Ans – Yes — EMIs are fixed, contractual obligations and belong in the needs bucket, not wants.
Q8. Can I save more than 20%?
Ans – Definitely — the 20% is a floor, not a ceiling. Higher savings rates simply accelerate wealth creation.
Final Thoughts
The 50-30-20 rule is one of the simplest, most sustainable ways for Indian salaried individuals to get their money under control. You don’t need a finance degree or a complicated spreadsheet — just your take-home salary, three buckets, and the discipline to automate the savings piece so it happens without relying on willpower every month.
Start with the percentages that fit your actual life, track loosely for a couple of months, and adjust from there. The goal isn’t a perfect 50-30-20 split — it’s a system you’ll actually stick with.
Disclaimer: This article is for educational and informational purposes only. Please consult a certified financial advisor such as one registered with SEBI before making investment or financial decisions.

Shilpesh Rathod is the founder of All Finance Knowledge. He holds a B.Com degree along with JAIIB and CAIIB banking certifications, and brings 19+ years of experience in the banking sector across savings, investments, and financial planning. Read more: https://allfinanceknowledge.com/about-us/
4 thoughts on “The 50-30-20 Rule in India: A Complete Guide with Real Salary Examples”