If you’ve ever hesitated before tapping “Check My CIBIL Score” on a banking app—worried that the simple act of looking might somehow cost you points—you’re far from alone. One of the most common questions borrowers ask is: Does checking CIBIL score reduce credit score? The answer is simple: No, checking your own CIBIL score does not reduce your credit score. However, when a lender checks your credit report as part of a loan or credit card application, it may be recorded as a hard inquiry and can have a small impact on your score. Understanding the difference between a soft inquiry and a hard inquiry can help you check your credit score without unnecessary worry.
Here’s the short version, right up front: checking your own CIBIL score does not reduce it. Not once, not a hundred times. You can check it every single day for the rest of your life and it will not move your score by even a single point on its own.
What can lower your score is something people often confuse with a simple check — applying for new credit. That distinction, between looking at your score and applying for a loan, is the entire mystery behind this myth, and it’s what this guide is going to unpack in detail.
By the end of this article, you’ll understand exactly how credit enquiries work, why the myth exists in the first place, how often you should really be checking your score, and what genuinely does move the needle on your CIBIL score — for better or worse.
Quick Answer: No, Self-Checks Are Completely Safe
Before we go deep into the mechanics, here’s the one-line takeaway you can act on immediately:
- Checking your own score (a “self-check”) = soft enquiry = zero impact, unlimited times.
- Applying for a loan or credit card = hard enquiry = small, temporary impact, should be limited.
Everything else in this article is really just an explanation of why that’s true and how to use it to your advantage.
What Exactly Is a CIBIL Score?
CIBIL, short for the Credit Information Bureau (India) Limited, is India’s oldest and most widely used credit bureau, now operating as TransUnion CIBIL. It collects repayment data from banks, NBFCs, housing finance companies, and credit card issuers, then converts that history into a three-digit number ranging from 300 to 900.
Think of it as a financial report card. Every EMI you pay on time, every credit card bill you clear, every loan you close responsibly — all of it gets reported to the bureau and folded into a running score that lenders use to judge how risky it would be to lend you money.
How the CIBIL Score Range Is Interpreted
| Score Range | Category | What It Means for You |
| 800–900 | Exceptional | Best interest rates, fastest approvals |
| 750–799 | Excellent | Strong approval odds, good rate negotiation |
| 700–749 | Good | Generally approved, standard rates |
| 650–699 | Fair/Average | Approvals possible but with caution or higher rates |
| Below 650 | Poor | High rejection risk, may need a co-applicant or secured loan |
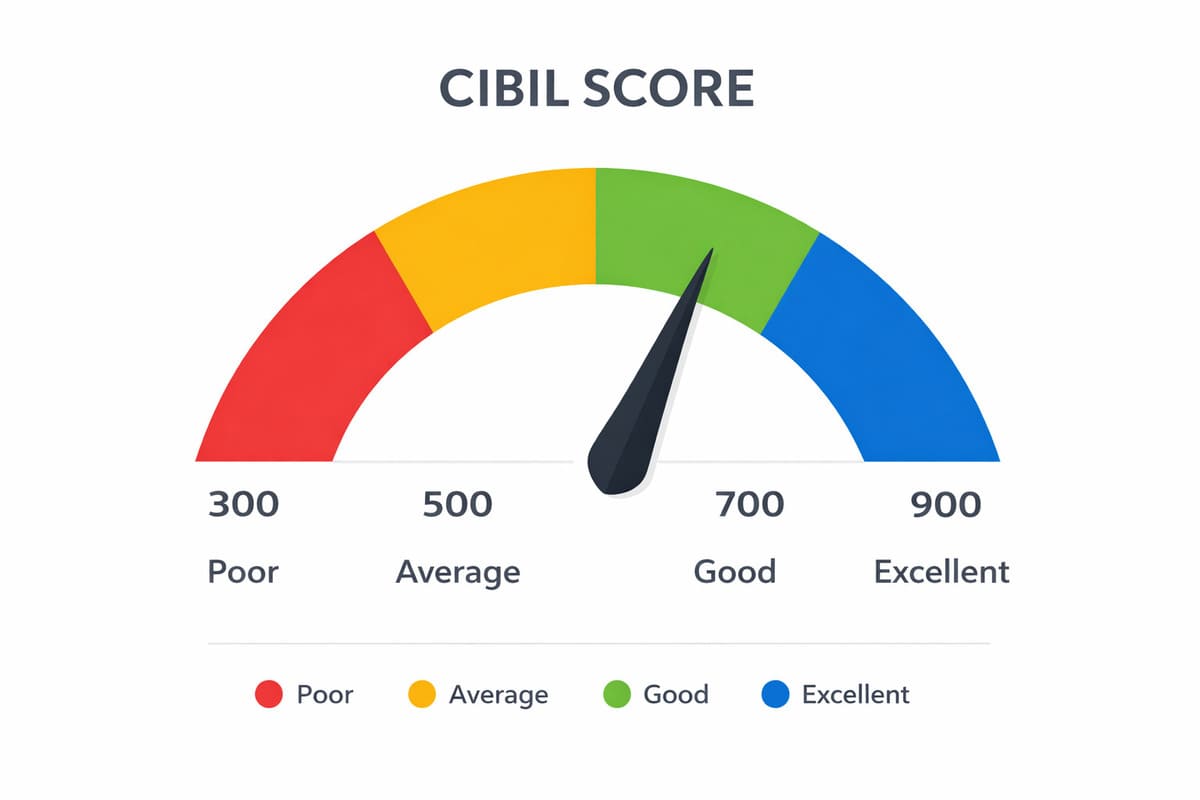
Most lenders in India set 700–750 as the practical cutoff for unsecured products like personal loans and premium credit cards, though this varies by lender and by how much of your income is already committed to other EMIs.
CIBIL isn’t the only bureau in the country, either. Equifax, Experian, and CRIF High Mark also operate in India under RBI licensing, and your score can differ slightly between them depending on which lenders report to which bureau and the exact scoring formula each one uses. CIBIL simply remains the most commonly referenced one because it was the first to launch in India and is still the bureau most banks pull from by default.
Does Checking CIBIL Score Reduce Credit Score? The Core Explanation
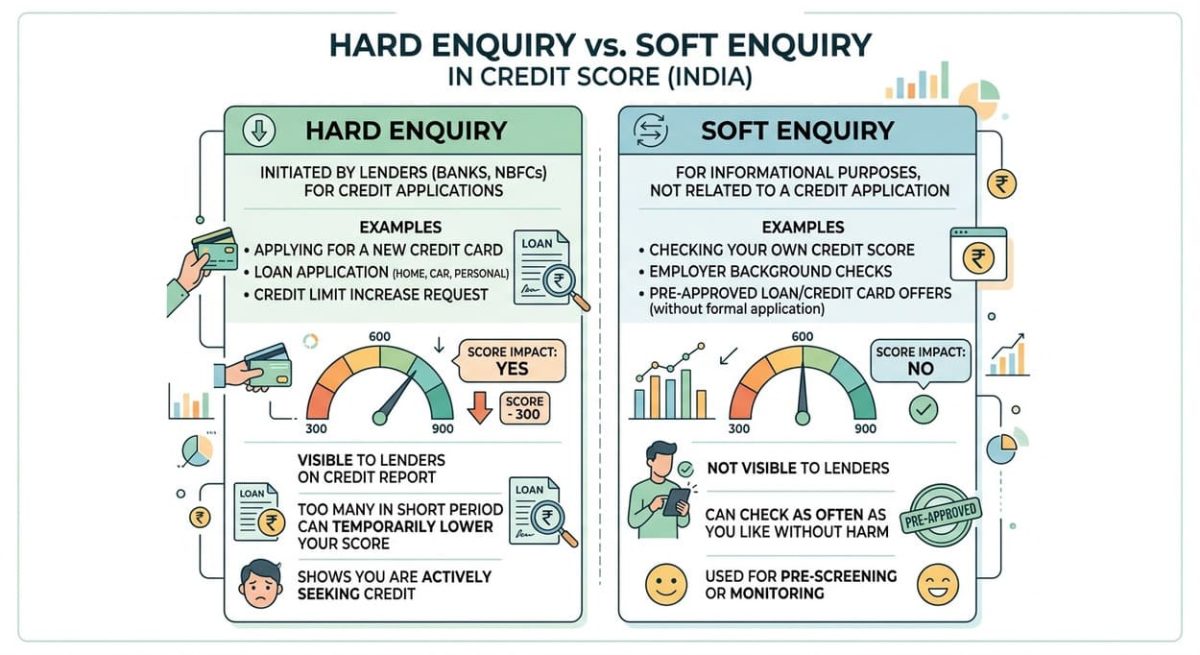
Now to the actual question. The confusion around this topic comes down to one missing piece of knowledge: not all credit “checks” are the same kind of event. Credit bureaus and lenders distinguish between two categories of enquiries, and only one of them has any bearing on your score.
Soft Enquiry: The Kind That Never Hurts You
A soft enquiry (sometimes called a “soft pull”) happens whenever your credit information is accessed but no lending decision is attached to that access. This includes:
- You logging into the official CIBIL portal, a bank’s mobile app, or a fintech app to see your own score
- A bank scanning your profile in the background to send you a pre-approved loan or card offer
- A credit-monitoring app refreshing your score automatically each month
- An employer running a background credit check (in specific, disclosed circumstances)
Soft enquiries are recorded on your report, but they are only visible to you — not to other lenders reviewing your file. Because no one is actually deciding whether to extend you credit at that moment, the bureau’s scoring model treats it as informational, not risk-relevant. That’s why it carries no score impact and no limit on frequency.
Hard Enquiry: The Kind That Can Nudge Your Score Down
A hard enquiry (or “hard pull”) is triggered when you formally apply for new credit and a lender pulls your report to make an approval decision. This includes:
- Submitting a personal loan, home loan, or car loan application
- Applying for a new credit card
- Requesting a credit limit increase on an existing card
- Co-signing or guaranteeing someone else’s loan
Each hard enquiry is visible to every lender who looks at your report afterward, and it typically shaves off somewhere in the range of 5 to 10 points, though the exact number depends on your overall credit profile. A single hard enquiry is a non-event in isolation — lenders expect people to occasionally apply for credit. The real damage comes from multiple hard enquiries clustered together in a short window (say, applying to five personal loan apps within two weeks), which signals to the bureau’s algorithm that you may be under financial stress and shopping desperately for approval.
Why the Myth Persists: A Simple Timeline Mix-Up
If checking your score is genuinely harmless, why do so many people swear their score dropped right after they checked it? The pattern almost always looks like this:
- Someone decides they want a loan, so they check their CIBIL score first to see where they stand.
- Feeling reasonably confident, they go ahead and apply for the loan a day or two later.
- The loan application triggers a hard enquiry, and the score dips slightly a few weeks after that, once the bureau processes the update.
- When they check their score again later, they see the drop and connect it — incorrectly — to the first check, not the loan application in between.
It’s a classic case of correlation being mistaken for causation. The self-check and the score drop happened close together in time, but the actual cause was the loan application sitting quietly in the middle of that sequence. Once you separate the two events, the myth falls apart on its own.
If you’ve noticed your score behaving unpredictably even without a recent loan application, it’s worth reading about why your CIBIL score might not be updating correctly, since reporting delays from lenders are another common source of confusion that gets wrongly blamed on score checks.
How Often Should You Actually Check Your Score?
Since soft enquiries carry zero cost, the real question isn’t “is it safe” but “how often is useful.” Checking daily won’t hurt you, but it’s also more than most people need. A practical rhythm looks like this:
- Once every 1–3 months as routine maintenance, so you always know roughly where you stand
- Right before applying for any significant loan or card, so you can time the application for when your score is strongest
- Immediately after closing a loan or paying off a credit card in full, to confirm the update reflected correctly
- During any active effort to rebuild your score, where monthly checks help you see whether your strategy — lower utilization, on-time payments, and so on — is actually working
There’s no rulebook that caps soft enquiries, so adjust this to your situation. Someone actively house-hunting and preparing for a home loan might check weekly; someone with stable finances and no borrowing plans might check twice a year and that’s plenty.
Why Checking Your Score Regularly Is Genuinely Good for You
Beyond simply debunking the myth, there’s a real case for making score-checking a habit rather than something to avoid.
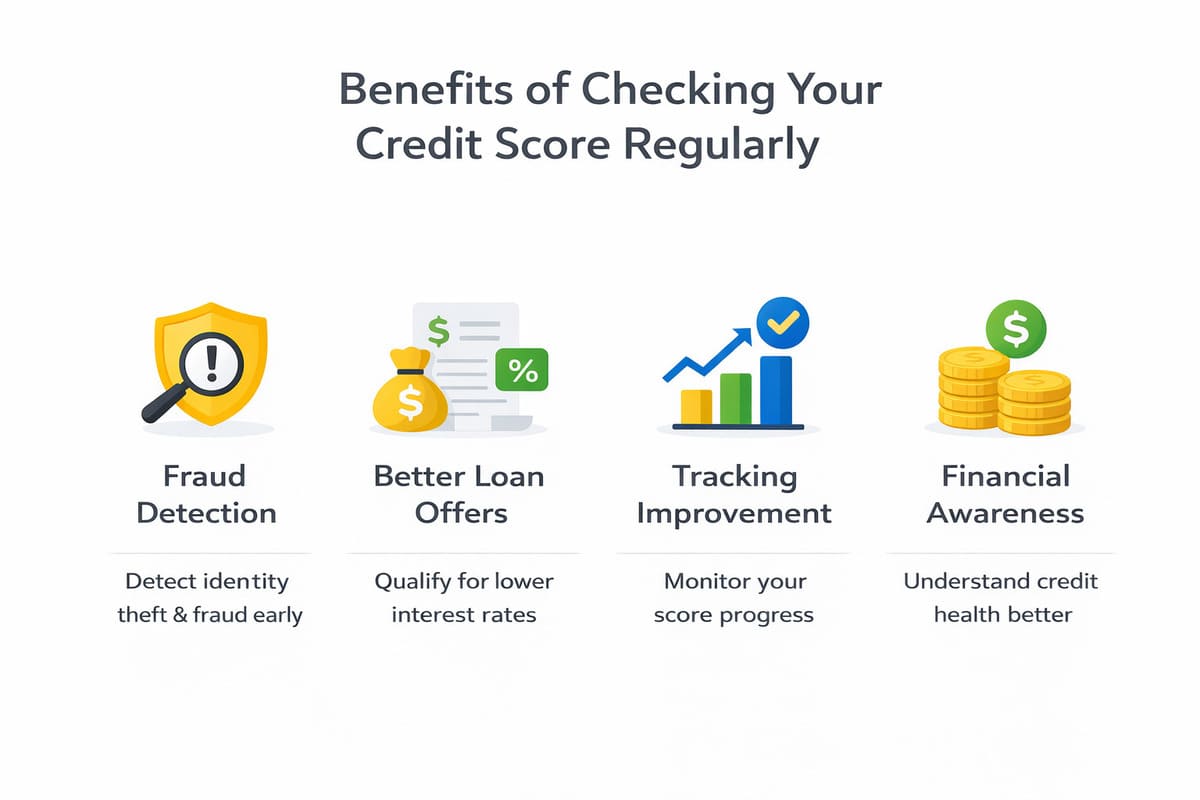
1. You Avoid Wasted, Rejection-Triggering Applications
Every rejected loan application still shows up as a hard enquiry with nothing to show for it. Checking your score beforehand lets you apply only when your odds are genuinely good, protecting your score from the compounding damage of repeated rejections.
2. You Gain Real Negotiating Power on Interest Rates
Lenders price risk into your interest rate. A borrower with a 780 score and one with a 650 score applying for the exact same loan amount can be offered meaningfully different EMIs over the loan tenure. Knowing your score ahead of time lets you walk into a negotiation — or shop between lenders — with actual leverage instead of guesswork.
3. You Catch Reporting Errors Before They Cost You
Credit reports aren’t infallible. A loan you closed years ago might still show as “active.” A payment you made on time might get logged as late due to a lender’s clerical error. These mistakes are more common than most people assume, and they can silently drag your score down for months if nobody catches them. Regular checks are how you catch them.
4. You Spot Signs of Identity Fraud Early
An account or credit card you never opened appearing on your report is often the first visible sign of identity theft. The earlier you spot it, the easier it is to dispute with the bureau and the lender before real damage — or real debt — accumulates in your name.
5. You Can Actually Measure Progress
If you’re rebuilding from a low score, watching the number move — even slowly — is one of the most motivating parts of the process. It turns an abstract goal (“improve my credit”) into something concrete you can track month over month.
If your starting point is on the lower end, this deeper walkthrough on how CIBIL scores work and how to improve them is a good next read, and this guide on raising a score from 550 to 750 lays out a concrete, step-by-step plan if you’re starting from a weaker position.
Checking Through Apps: Is It Different From the Official Website?
A related worry people have is whether checking through a third-party app — rather than the official CIBIL site — somehow counts differently. It doesn’t, as long as the app is doing what it claims to be doing: pulling a soft enquiry on your behalf with your consent.
Signs an app is doing this safely:
- It clearly states it performs a “soft pull” or “soft enquiry”
- It’s operated by a regulated bank, NBFC, or a company licensed to access bureau data
- It doesn’t ask for banking credentials or OTPs beyond what’s needed for identity verification
- The score shown matches (or is close to) what you’d see on the official bureau site
Reasonable, trustworthy places to check your score include:
- The official CIBIL website, which offers one free report per calendar year directly from the source
- Your own bank’s or credit card issuer’s mobile app, which often shows your score for free as a value-added feature
- Established financial apps that are transparent about being RBI-regulated or bureau-partnered
Be more cautious with apps that ask for excessive permissions unrelated to a credit check — access to your contacts, SMS messages, or storage, for instance — since that’s a data-privacy concern separate from (but sometimes bundled with) score-checking tools.
Common Myths About CIBIL Score Checking, Debunked
It helps to line up the most common misconceptions side by side with what’s actually true.
Myth: “Checking my score multiple times a month will drag it down.” Reality: Frequency of self-checks has no bearing on your score whatsoever. The bureau’s algorithm simply doesn’t factor soft enquiries into the score calculation.
Myth: “Free credit score checks are a scam or inherently unsafe.” Reality: Free annual reports are a right, not a gimmick — RBI has mandated that every credit information company provide consumers at least one free full report per year. Many banks and apps offer more frequent free score views as a customer-retention feature, which is a legitimate business model, not a trap.
Myth: “Only banks and lenders are allowed to see my credit score.” Reality: It’s your data. You are always entitled to view your own credit report and score, in full, whenever you like.
Myth: “A hard enquiry permanently damages your score.” Reality: The dip from a hard enquiry is typically small and temporary. With normal on-time repayment behavior afterward, scores generally recover within a few months.
What Actually Causes a CIBIL Score to Drop
Since checking your score is off the table as a cause, it’s worth being clear-eyed about what genuinely does move your score downward, so you know what to watch for instead.
- Missed or late EMI payments — even a single payment reported 30+ days late can have an outsized effect, and the impact grows with how overdue the payment is
- High credit utilization — regularly using more than 30% of your total credit card limit signals reliance on borrowed money, even if you pay it off every month
- Loan settlements instead of full closures — settling a loan for less than owed is recorded differently than a full closure and tends to hurt your score for years afterward
- Too many hard enquiries in a short period — multiple loan or card applications within weeks of each other
- Defaults and write-offs — the most severe category, where a lender has given up on recovering the debt through normal means
- A short or thin credit history — even with responsible behavior, having very few accounts or a short track record can cap how high your score climbs
None of these have anything to do with logging in to look at a number. They’re all tied to how you actually borrow and repay, which is exactly what a credit score is designed to measure.
Advanced Tips to Protect and Grow Your Score Over Time
Once the “does checking hurt me” question is settled, the more useful question becomes: what should you actively be doing to keep the number climbing?
Keep Utilization Comfortably Under 30%
If your total credit card limit across all cards is ₹2,00,000, try to keep your outstanding balance under ₹60,000 at any given time, even if you plan to pay it off in full before the due date. Utilization is often calculated from the statement date, not the due date, so high spending mid-cycle can still show up as high utilization even if you clear it later.
Diversify Your Credit Mix, Sensibly
A blend of secured credit (like a car or home loan) and unsecured credit (like credit cards or a personal loan) tends to be viewed more favorably than relying on only one type — though this should never be a reason to take on debt you don’t need. Let your credit mix develop naturally from products you’d use anyway.
Think Twice Before Closing Old Accounts
The length of your credit history matters, and your oldest accounts are doing more work for your score than you might realize. Closing your first-ever credit card, even one you rarely use, can shorten your average account age and slightly hurt your score. If there’s no annual fee pressure, it’s often better to keep old, dormant accounts open.
Pay More Than the Minimum Due
On credit cards especially, paying only the minimum due keeps you technically “current” but allows interest to compound on the rest, and it does nothing to improve your utilization ratio. Paying the statement balance in full each cycle is one of the single highest-leverage habits for both your score and your finances generally.
Set Up Auto-Pay for At Least the Minimum
The single most damaging thing you can do to your score is miss a payment altogether. Auto-pay for at least the minimum due acts as a safety net against forgetfulness, even if you plan to manually pay the full balance.
A Realistic Example
Suppose Priya has a CIBIL score of 742. She checks it on her banking app once a month out of habit — no impact, month after month. In March, she starts comparing personal loan offers and checks her score twice more that week to time her application well. Still no impact; these are all soft enquiries.
She applies to one lender in March. That application triggers a hard enquiry, and by the time her next statement cycle closes, her score has dipped to around 735 — a small, expected move. She gets approved, borrows what she needs, and starts repaying on schedule. Four months later, with a clean repayment record and no further applications, her score has recovered to 748, slightly higher than where she started, because on-time repayment is itself a positive signal to the bureau over time.
Nowhere in that story did the act of checking cost her anything. The only score-relevant event was the loan application itself, and even that was a temporary, recoverable dip.
Frequently Asked Questions
1. Does checking my CIBIL score online reduce my points?
Ans – No. Any self-initiated check — whether on the official CIBIL site, a bank app, or a reputable financial app — is a soft enquiry, and soft enquiries have no effect on your score.
2. How many points does a hard enquiry actually cost?
Ans – Typically somewhere between 5 and 10 points for a single enquiry, though the exact figure depends on your overall credit profile. This is usually recovered within a few months of continued on-time repayment.
3. Is it safe to check my score every single month?
Ans – Yes, completely. There’s no cap on soft enquiries, and checking monthly is actually a reasonable habit for staying on top of your financial health.
4. Can lenders see how many times I’ve checked my own score?
Ans – No. Self-checks are visible only to you on your own report; they don’t appear to lenders reviewing your file for a lending decision.
5. Should I check my CIBIL score before applying for a loan?
Ans – Yes. Checking beforehand lets you apply only when your score is strong enough for good approval odds and competitive interest rates, which protects you from the double cost of a rejection plus an unnecessary hard enquiry.
6. Does a free CIBIL score check from an app affect accuracy?
Ans – Not necessarily — free score displays from regulated banks and apps typically pull real bureau data via soft enquiry. Minor differences between apps can occur due to which bureau they pull from or slight timing differences in when data was last refreshed, not because the check itself changed anything.
7. Will my score go up simply because I stop checking it?
Ans – No — checking or not checking has no bearing either way. Your score moves based on repayment behavior, utilization, and account history, never based on how often you look at it
Final Thoughts
The fear that checking your CIBIL score might lower it is one of the most widespread pieces of financial misinformation in India, and it’s also one of the easiest to correct once you understand the mechanics. Self-checks are soft enquiries. Soft enquiries carry zero weight in the bureau’s scoring formula. The only credit event that genuinely nudges your score is a hard enquiry — and that only happens when you’re actually applying for new credit, not when you’re simply looking at where you stand.
If anything, avoiding your credit report out of unfounded caution is the more costly habit. Regular, informed monitoring helps you time applications well, catch errors before they snowball, spot fraud early, and stay motivated while building toward a stronger score.
Make peace with checking your score as often as you find useful — monthly is a sensible default for most people — and reserve your caution for what actually matters: paying on time, keeping utilization low, and applying for new credit only when you genuinely need it.
For a broader foundation on managing your money well beyond just your credit score, this guide on the basics of personal finance planning is a solid next stop, and if you’re weighing borrowing options, this comparison of personal loans versus credit card loans can help you choose the cheaper, smarter option for your situation.
You can also verify current rules on free annual credit reports directly through the Reserve Bank of India’s guidelines on credit information companies or pull your official report anytime from TransUnion CIBIL’s website.
Disclaimer: This article is for general informational purposes only and does not constitute financial or legal advice. Credit scoring rules, free-report policies, and enquiry impacts can vary by bureau and by lender, and may change over time. Always confirm current details with the official bureau or your lender before making financial decisions.

Shilpesh Rathod is the founder of All Finance Knowledge. He holds a B.Com degree along with JAIIB and CAIIB banking certifications, and brings 19+ years of experience in the banking sector across savings, investments, and financial planning. Read more: https://allfinanceknowledge.com/about-us/
4 thoughts on “Does Checking CIBIL Score Reduce Credit Score? The Truth About Hard vs Soft Enquiries”